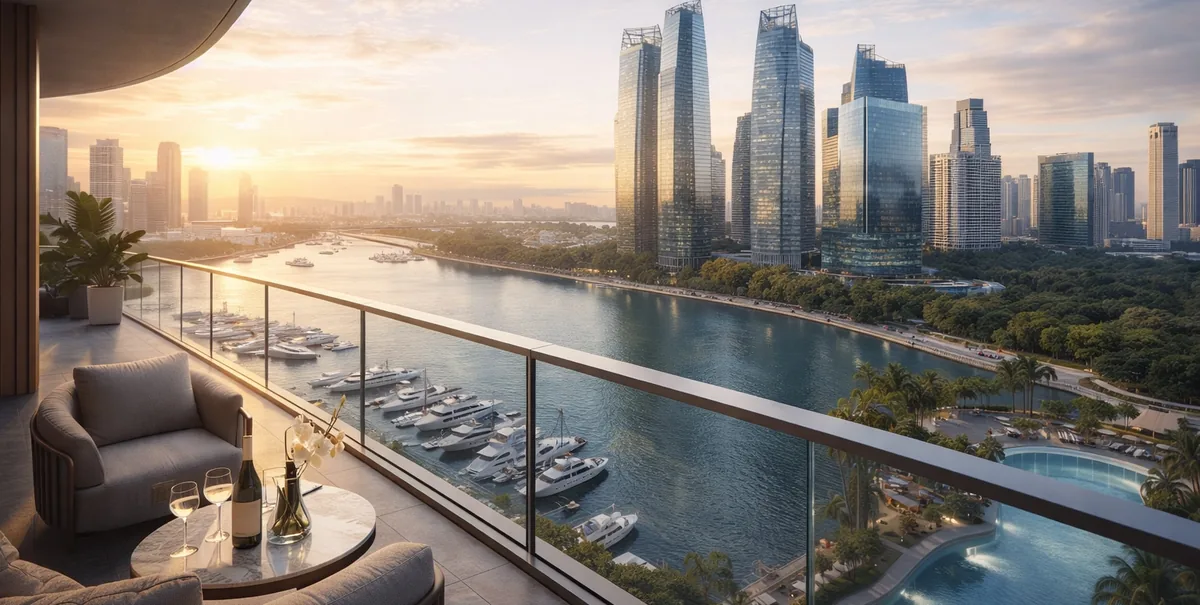
 Artist’s impression. Illustrative only, not the development.
The Short Answer for The Island Residence
Homes at The Island Residence will be sold before completion, on the normal progressive payment scheme for a building under construction. The buyer pays 5% to book, 15% on signing the sale and purchase agreement, then further instalments as each stage of construction is certified, with 25% on the Temporary Occupation Permit and the final 15% on the Certificate of Statutory Completion.
Because the instalments follow the building, the bank’s loan is drawn in stages too, and interest is paid only on the amount drawn. That is the main reason a new launch is easier on cash flow in its early years than a completed home.
The Payment Stages at The Island Residence
The stages are set by the Housing Developers Rules. After the 5% booking fee and the 15% on signing, the buyer pays 10% on completion of the foundation, 10% on the reinforced concrete framework, 5% each on the partition walls, the roofing and ceiling, the doors, windows, wiring and plumbing, and the car park, roads and drains, then 25% on TOP and 15% on statutory completion.
Where some stages have already been certified when a home is booked, those instalments fall due on the timetable in the sale and purchase agreement. The full table is on the payment scheme page.
Cash, CPF and the Loan at The Island Residence
Before the bank lends anything, the buyer pays their own share of the price. For a buyer with no outstanding housing loan and a tenure of 30 years or less that ends by age 65, the bank may lend 75%, so the buyer’s share is 25%: at least 5% in cash, which the booking fee covers, and the other 20% from cash or CPF Ordinary Account savings within CPF rules.
A loan with a tenure over 30 years, or one running past the borrower’s 65th birthday, falls into a lower band of 55%, with at least 10% in cash. A buyer with one housing loan outstanding may borrow 45% and pays at least 25% in cash. The housing loan page sets these out in full.
A Worked Example for The Island Residence
Take $2,000,000, an illustrative figure that bears no relation to the pricing of The Island Residence, and a Singapore Citizen buying a first home with a 75% loan. The booking fee of $100,000 is paid in cash. Within about eight weeks the 15% on signing, $300,000, brings the buyer to 20%, and half of the 10% foundation instalment, another $100,000, completes the buyer’s 25%.
From then on the bank pays each certified stage, and the repayment grows with it. Buyer’s Stamp Duty of $69,600 is due separately within 14 days of signing. The progressive payment calculator shows the drawdown and the estimated monthly instalment at every stage for any price, tenure and rate.
Planning the Timeline at The Island Residence
The developer will state the expected dates of vacant possession and legal completion in its documents at release, and those dates set when the larger instalments fall due. For a household that already owns a home and plans to sell it, the timing matters: the first 20% is paid at the start, but the 25% on TOP and the final 15% fall due only as the building nears completion.
The order of selling and buying changes both the loan and the duty. A buyer who still has a housing loan when booking is limited to a 45% loan, and a Singapore Citizen buying a second residential property pays 20% ABSD, which a married couple may have refunded if they sell their first home within the period IRAS allows. The stamp duty page explains both rules, and the Sales Concierge can prepare a schedule for a chosen home at a preview appointment.
Why the Progressive Scheme Suits The Island Residence Buyers
The progressive scheme matches payments to progress. A buyer pays a fifth of the price in the first weeks, and the larger sums fall due as the building is completed and becomes a home that can be occupied, let or sold. For a buyer who is selling an existing home, that leaves time to plan the sale around the later instalments rather than ahead of the booking.
It also keeps the interest bill small during construction. Because the bank pays each stage only when it is certified, interest runs only on the amount drawn, and the full monthly instalment begins near the end of the build. The progressive payment calculator shows how the instalment grows from stage to stage.
One figure deserves attention early: the cash. The booking fee must be paid in cash, stamp duty is paid in cash first and reimbursed from CPF only where CPF rules allow, and a buyer in the lower loan-to-value band needs at least 10% of the price in cash. Knowing that figure before the preview avoids a shortfall at the most time-sensitive point of the purchase.
Talk to the Sales Concierge About The Island Residence
The Sales Concierge sends the official name, the e-brochure, the floor plans and the price list for The Island Residence on release, and arranges a private preview appointment.